Venmo

Screenshots
Details
- Rating
- 344.28K reviews
- Version
- 10.80.0
- Developer
- Venmo
Analysis by Norviv
I find Venmo most useful when a payment needs to happen between people who already know one another. The app is designed around sending and requesting money, with notes that help explain what a transfer is for. That makes it a natural fit for settling shared costs, but it is not the same thing as a full budgeting tool or a replacement for every way of paying. I’d choose it for the small, everyday exchanges where a clear record is handy and both people are comfortable using the service.
When a payment depends on a good connection
Connectivity is part of the experience, not a detail I’d ignore. Starting a payment, checking whether a request has been handled, or looking back at a transaction all depend on being able to reach the app and its service. If I’m in a basement restaurant or somewhere with patchy mobile reception, I don’t treat a screen that hasn’t updated as proof that a payment failed. I wait until the connection is stable, check the activity again, and avoid sending a second payment in a hurry.
That small pause is useful because money apps reward accuracy more than speed. Before confirming, I check the recipient and the amount, then make sure the note identifies the shared expense without putting private details in it. If the other person is standing beside me, I can compare what we each see. If they aren’t, I send a quick message through our usual channel rather than assuming a delayed notification means they have not received anything.
The social feed can make routine transfers feel casual, but the underlying action is still financial. I like the friendly tone for a coffee or a shared meal; I switch to a more deliberate approach for larger amounts or an unfamiliar recipient. A reliable connection helps me review the details, but it does not replace that second look.
Useful in everyday mobile situations
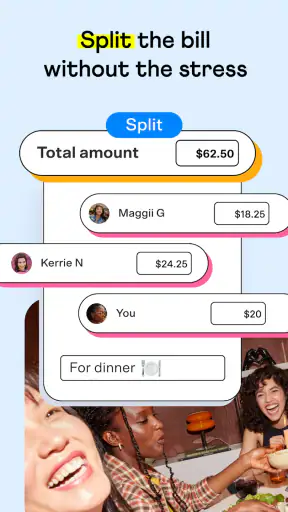
A realistic example is a group dinner where one person pays the restaurant and everyone else needs to settle up afterward. The person who covered the bill can request the appropriate shares, and the note can say what the request concerns. I’d agree on the split first, especially if some people ordered much more than others, rather than letting the convenience of a quick request decide what feels fair. Venmo can make collecting easier; it cannot resolve a disagreement about the bill.
It also suits less formal arrangements: paying a friend back for tickets, sharing a household purchase, or contributing to a gift. Those uses benefit from a short, recognizable note, because a payment history is more useful when I can tell one transfer from another later. I keep the wording simple and avoid treating the note field like a private conversation, particularly when I have not checked who can see the activity.
On a phone, the quick flow is the appeal, but the setting matters. I would not rush through a payment while walking across a busy street or hand my unlocked phone to someone else to enter details. If I’m in a hurry, it is better to stop, check the recipient, and finish the transfer carefully than to correct a mistake afterward. That is a practical trade-off: the app reduces the awkwardness of asking for money, but it still expects the user to pay attention.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Recovering from uncertainty without paying twice
If a transaction appears to stall, I first check the connection and then review the activity before trying again. Repeating the same action immediately is the risky response, since the first attempt may have gone through even if the screen did not refresh as expected. I also check the recipient spelling and payment note. For a request, I confirm whether I’m looking at the request or the completed payment; those are different actions, and mixing them up can create confusion.
For an amount or recipient that looks wrong, I would not assume that a later tap will neatly undo it. I pause, inspect the transaction details, and contact the person involved through a separate channel if needed. Keeping the note specific enough to identify the expense can make that conversation easier. This is one reason I see Venmo as best for people-to-people payments with clear context, rather than as a carefree substitute for cash in every situation.
Notifications are convenient reminders, but I treat the activity view as the place to verify what happened. A notification can be missed, delayed, or easy to misread when I’m busy. The useful habit is to confirm the actual transaction before telling someone they have been paid or asking them to send money again. That extra check takes little effort and prevents a minor network hiccup from becoming a duplicate-payment problem.
Privacy, records, and the right payment tool
The social layer is distinctive compared with more conventional bank apps, but not everyone wants financial activity to feel social. Venmo provides controls for who can see transactions, so I’d review those settings and choose deliberately rather than leaving visibility to chance. I also keep payment notes practical and restrained. Even when a transaction is visible only to a chosen audience, there is no good reason to put sensitive personal information in a casual description.
For someone who mainly wants to transfer money between friends, that blend of payment and social context can feel more approachable than opening a traditional banking app for every small repayment. A bank transfer may be a better fit when I want all activity handled within my existing banking relationship, while cash remains simpler for a one-off exchange when both people are together. The best choice depends on what the other person can use and how much record-keeping the situation needs; convenience only works when both sides agree on the method.
I would also separate these casual settlements from serious financial tracking. A history of payments can help me remember who covered a shared expense, but it is not the same as a household budget that categorizes spending and plans upcoming bills. If my main goal is to monitor monthly expenses, I’d use a budgeting approach alongside it rather than expecting payment notes to do that job. That distinction helps keep a handy transfer app from becoming the center of a system it was not designed to replace.
Who is likely to get the most from it?
Venmo is a strong match for people whose friends, relatives, or roommates already use it and who regularly settle small shared costs. It can reduce the need to remember who owes what after meals, tickets, or group purchases. It is less compelling if nearly everyone I pay prefers another service, if I want a private, purely banking-focused experience, or if I need detailed budgeting and financial planning in the same place. In those cases, the familiar bank app, cash, or a dedicated finance tool may be the more sensible choice.
There is also a practical boundary around trust. I’m comfortable using a person-to-person payment app when I know who I’m paying and understand the reason for the transfer. For a purchase from a stranger, I would not assume that a convenient payment flow gives me the protections or dispute process I want from a dedicated checkout method. I choose the payment method based on the relationship and the transaction, not just on which app opens fastest.
Venmo is a free finance app from developer Venmo, and it has been available since May 17, 2010. It has a 4.1 average from around 881,000 ratings, with over 50 million installs. The current version is 10.80.0, and it is rated Everyone; its listed minimum operating-system requirement is version 8.0. Those details point to a long-established, widely used option, though popularity does not make it the right fit for every payment habit.
Getting Started with Venmo
First things first, setting up Venmo is as smooth as a buttered slide. After downloading the app from your favorite app store, you just need to create an account. You can sign up using your email or link it directly to your Facebook. Once that’s done, connect your bank account or debit card, and you’re good to go.
The interface is super user-friendly. The home screen shows your balance and recent transactions from you and your friends. It’s like a social media feed, but for money. You can even like and comment on transactions if you’re feeling chatty.
The Venmo Experience
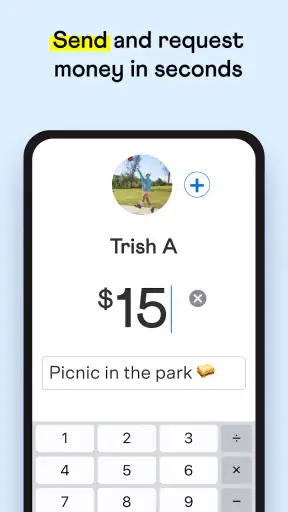
The best part about Venmo is how easy it makes sending and receiving money. Need to pay back a friend for concert tickets? Just tap on “Pay or Request” and enter the amount. You can add a note to remind your friend what the payment is for, and even throw in an emoji if you're feeling playful.
But wait, there's more! Venmo also has a handy feature called “split payment.” If you’re out with friends and it’s time to settle the bill, just split the amount among your group. Everyone gets a notification to pay their share, and you avoid the awkward "who owes who" conversation.
Security and Privacy
Now, I know what you’re thinking—how safe is my money on Venmo? Well, they’ve got your back with encryption and security measures to keep your info safe. You can also set up a PIN and enable fingerprint recognition for an added layer of security. Just remember to keep an eye on your transactions and report anything fishy.
If privacy is a concern, Venmo lets you control who sees your transactions. You can set each payment to be public, visible to friends, or private. It’s all about what you’re comfortable with.
Final Thoughts
In a world where cash is becoming obsolete, Venmo is a game-changer. It’s seamless, social, and secure—everything you want in a payment app. The convenience it offers is unmatched, and it’s become an essential tool in my digital wallet. So, if you haven’t tried it yet, give Venmo a spin. Trust me, you’ll wonder how you ever managed without it!
My practical verdict on staying connected
For me, the best reason to use Venmo is that it makes a familiar social obligation—paying someone back—easier to handle and easier to remember. The app’s social style is not essential to the transfer itself, and I would not use public activity as a substitute for a private conversation or a proper receipt. I’d keep visibility settings intentional, write notes that identify expenses without revealing personal details, and verify activity when a connection has been unreliable.
That makes my recommendation fairly specific: try it if the people you regularly settle up with are already comfortable using it and you want a straightforward way to manage those exchanges. Skip it, or pair it with another method, if your priority is comprehensive budgeting, entirely private banking, or payments to people you do not know. Venmo works best when the connection is steady, the recipient is familiar, and both sides know exactly what the payment is for.
Frequently Asked Questions
01What is Venmo and how does it work?
Venmo is a mobile payment service that allows users to transfer money to one another using a mobile phone app. It's widely used for splitting bills, paying friends, or purchasing goods and services from authorized merchants. Users can link their bank accounts, debit, or credit cards to the app to fund their transactions.
02Is Venmo safe to use for transactions?
Yes, Venmo employs several security measures to protect users' information, such as data encryption and multi-factor authentication. However, users should still exercise caution by not sharing their login information and only using the service with people they trust. Venmo also offers purchase protection for eligible transactions.
03Are there any fees associated with using Venmo?
Venmo is free to use for sending money from a bank account, debit card, or Venmo balance. However, there is a 3% fee for sending money using a credit card, and an instant transfer fee if you want to move funds to your bank account more quickly than the standard one to three business days.
04Can I use Venmo internationally?
Venmo is currently only available to users within the United States. Transactions can only be made with U.S. bank accounts and phone numbers. If you need to send money internationally, you might want to explore other options that support cross-border payments.
05How do I resolve issues with a Venmo transaction?
If you encounter a problem with a Venmo transaction, you can contact Venmo’s customer support through the app or website. They offer assistance with unauthorized transactions, payment errors, and other issues. It's also a good idea to double-check transaction details before confirming any payments.


